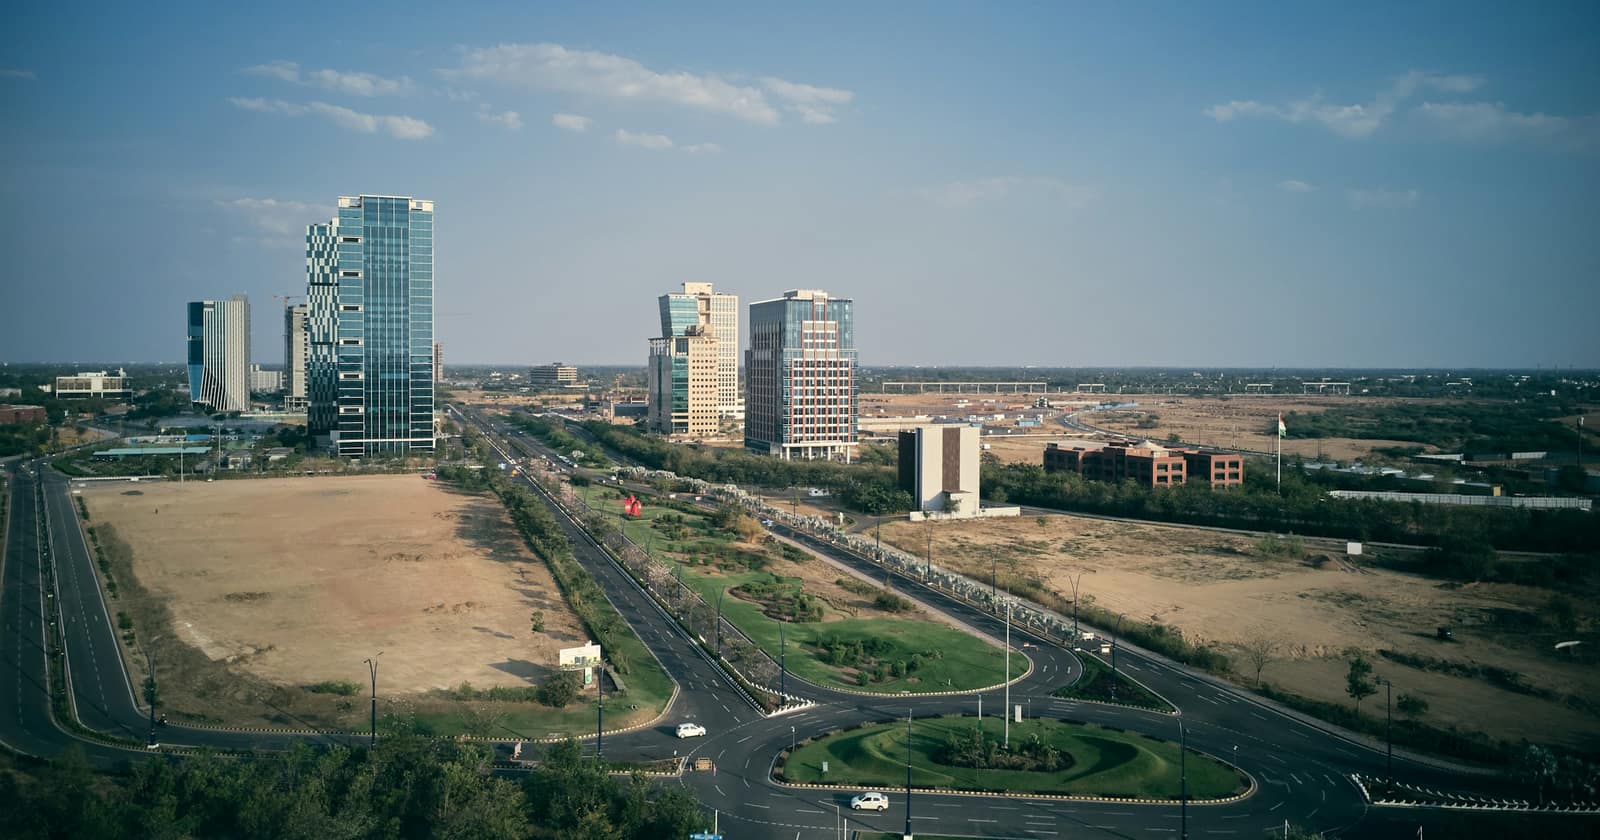
Drive north out of Ahmedabad towards Gandhinagar and the skyline changes abruptly. A cluster of glass towers rises out of flat Gujarat farmland, with a clean grid of roads laid out for buildings that are still arriving. This is GIFT City, home to an International Financial Services Centre, which section 2(61) of the Income-tax Act defines by reference to the Special Economic Zones Act, 2005.
What brings banks, funds, aircraft lessors and fintech companies here isn't the architecture. It is a tax regime that, under the Income-tax Act, 2025 and after the Finance Act, 2026, has become one of the most generous in the country. Here is what it offers, and to whom.
The headline: twenty years out of twenty-five
For an IFSC unit, the core benefit is section 147, the successor to section 80LA. It allows a deduction of 100% of the income from the unit's approved business activities.
The Finance Act, 2026 lengthened it considerably. Until 31 March 2026, the deduction ran for any 10 consecutive years out of 15. From 1 April 2026, it runs for any 20 consecutive tax years out of 25, beginning with the year the unit received its permission or registration, at the unit's choice.
Two conditions come with it. The unit has to file a chartered accountant's report in Form 35, and, for units starting on or after 1 April 2026, it must not be formed by splitting up or reconstructing a business already in India. A new structure is welcome; an old one repackaged is not.
Other benefits for units
- 9% minimum tax. An IFSC unit that earns solely in convertible foreign exchange pays minimum alternate tax, or alternate minimum tax, at 9%, under section 206. For other companies, the Finance Act, 2026 has just cut MAT from 15% to 14%.
- The deduction survives the new regimes. A company in the 22% regime, and an individual in the default new regime who runs an IFSC unit, still keep the section 147 deduction.
- After the holiday. The Finance Act, 2026 also added section 218, which taxes the income of an IFSC unit's approved activities at 15%. How it works alongside the section 147 deduction is a question for each unit's advisers.
For non-residents: the reason capital flows in
- Not a transfer at all. Under section 70(1)(r), when a non-resident sells bonds, GDRs, rupee-denominated bonds or derivatives on an IFSC exchange for foreign currency, it isn't a "transfer", so there is no capital gain to tax.
- Interest. Interest paid by an IFSC unit on money it borrowed on or after 1 September 2019 is exempt in the lender's hands (Schedule VI).
- Funds. Income from a specified IFSC fund, and on transferring its units, is exempt for unit holders. The funds themselves are exempt on specified income to the extent it belongs to non-resident investors.
- Dividends. A dividend from an IFSC unit to a non-resident is taxed at 10%, against 20% for other dividends, under section 207.
- No PAN. Under rule 157(3), a foreign investor who deals only in these IFSC-listed assets, and meets the conditions, need not obtain a PAN at all.
For resident individuals
GIFT City isn't only for foreigners and institutions, though the personal benefits are narrower:
- Trading on an IFSC exchange. Equity trades settled in foreign currency get the same capital gains rates as domestic listed equity, 20% short-term and 12.5% long-term, without the securities transaction tax condition (sections 196(3) and 198(4)).
- Life insurance. A policy issued on or after 1 April 2025 by an IFSC insurance office is not held to the ₹2,50,000 and ₹5,00,000 annual-premium limits that otherwise remove the maturity exemption (Schedule II).
GIFT City's tax regime was built to make India the place where Indian money, and foreign money headed for India, no longer has to leave the country to be managed.
Find yours
Which GIFT City benefit applies to you?
- Bonds, GDRs, rupee-denominated bonds and derivatives sold on an IFSC exchange for foreign currency are not treated as a transfer at all.Section 70(1)(r)
- Interest paid by an IFSC unit on money it borrowed on or after 1 September 2019 is exempt.Schedule VI, Sl. 12
- Income from, and on transfer of units in, a specified fund is exempt for its unit holders.Schedule VI, Sl. 9
- Dividends from an IFSC unit are taxed at 10%, against 20% for other dividends.Section 207
- Income from offshore derivative instruments entered into with an IFSC banking unit or FPI unit is exempt.Schedule VI, Sl. 5
- An eligible foreign investor trading only these IFSC-listed assets need not obtain a PAN, if the conditions are met.Rule 157(3)
Income-tax Act, 2025 as amended by the Finance Act, 2026: sections 70, 147, 196, 198, 202, 206, 207, Schedules II and VI; Income-tax Rules, 2026, rules 157 and 220. Each benefit carries conditions in its section; read it before relying on it.
Funds moving home
Funds that relocate from abroad to an IFSC, by 31 March 2030, can transfer their assets, and their investors can swap units, without it being treated as a transfer (section 70(1)(t) and (u)). The exemption follows the gains through to the relocated fund.
Where this comes from
The law is the Income-tax Act, 2025 as amended by the Finance Act, 2026: sections 2(61), 70, 147, 196, 198, 200, 202, 206, 207 and 218, and Schedules II and VI. The procedure is rules 69, 157 and 220 of the Income-tax Rules, 2026. Every benefit carries conditions in its own section, from foreign-currency settlement to commencement dates, and those conditions decide whether it applies.
Questions this answers
What is the tax holiday for GIFT City units?
100% of the income of approved activities under section 147 of the Income-tax Act, 2025, for any 20 consecutive tax years out of 25, after the Finance Act, 2026.
What is the MAT rate for an IFSC unit?
9%, under section 206, where the unit derives its income solely in convertible foreign exchange.
What tax benefits do NRIs get in GIFT City?
Among others, their sales of bonds, GDRs, rupee bonds and derivatives on an IFSC exchange for foreign currency are not transfers under section 70(1)(r), and interest from IFSC units on money borrowed on or after 1 September 2019 is exempt.
Are there GIFT City tax benefits for resident individuals?
Yes, narrower ones: foreign-currency equity trades on an IFSC exchange keep the capital gains rates without the STT condition, and IFSC life insurance policies escape the premium limits for the maturity exemption.
What is the dividend tax rate from an IFSC unit for non-residents?
10% under section 207 of the Income-tax Act, 2025, against 20% for other dividends.
Read next
- Crypto Tax in India in 2026: 30%, the 1% TDS, the Loss You Can't Use, and What the Platforms Really Report
- AI in Audit: What a Chartered Accountant Can Rely On, and What NFRA and the Standards Still Demand
- Startups in 2026: Angel Tax Is Gone, the Tax Holiday Now Reaches ₹300 Crore, and When ESOP Tax Really Falls Due